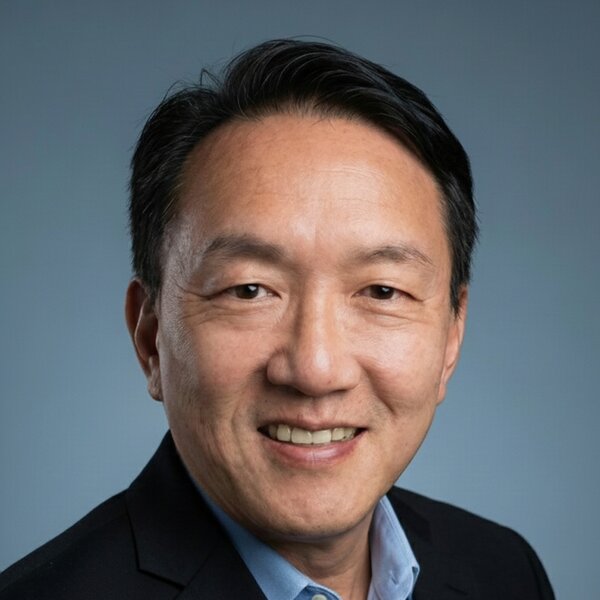
You're getting guidance from the source — Jae Oh
Jae Oh literally wrote Maximize Your Medicare, the widely referenced guide now in its 2026–2027 Edition. This isn't a call-center script or a generic lead form — it's the same expertise that's helped countless people navigate the transition from employer coverage, COBRA, and ACA into Medicare without the costly, irreversible mistakes.
- 📘 Published Author
- ✅ Federally Certified
- 🎓 Recognized Medicare Authority
- 🗣️ Plain-English Guidance
Employer / COBRA / ACA → Medicare: what changes?
Each path into Medicare has its own timing rules. Get one wrong and the penalty can follow you for the rest of your life. Here's the short version.
| Your situation | The risk | What you need to know |
|---|---|---|
| Leaving employer coverage at 65+ | Special window | You usually get an 8-month Special Enrollment Period — but it starts ticking the moment coverage (or employment) ends. |
| On COBRA | High risk | COBRA does not count as active coverage for Medicare. Waiting can trigger lifetime Part B penalties. |
| On an ACA / Marketplace plan | High risk | Marketplace subsidies typically end at Medicare eligibility. Keeping ACA too long can cost you twice. |
| Skipping Part D (drug plan) | Permanent | The Part D late penalty is added to your premium for life — even if you don't take medications now. |
What happens after you submit
No call center. No runaround. Just a clear plan built around your situation.
Tell us your situation
The short form above takes about 30 seconds. We use it to understand your timing and coverage.
Get expert guidance
We review your options — penalties, deadlines, and the right plan type for you — drawing on the same expertise behind the book.
Get a clear plan
You'll know exactly what to do and when. Enroll with confidence, or just walk away informed. Always free.
Don't gamble with a lifetime penalty.
Get free, personalized Medicare guidance from the author of Maximize Your Medicare. It costs you nothing and could save you thousands.
Get My Free Medicare Plan →